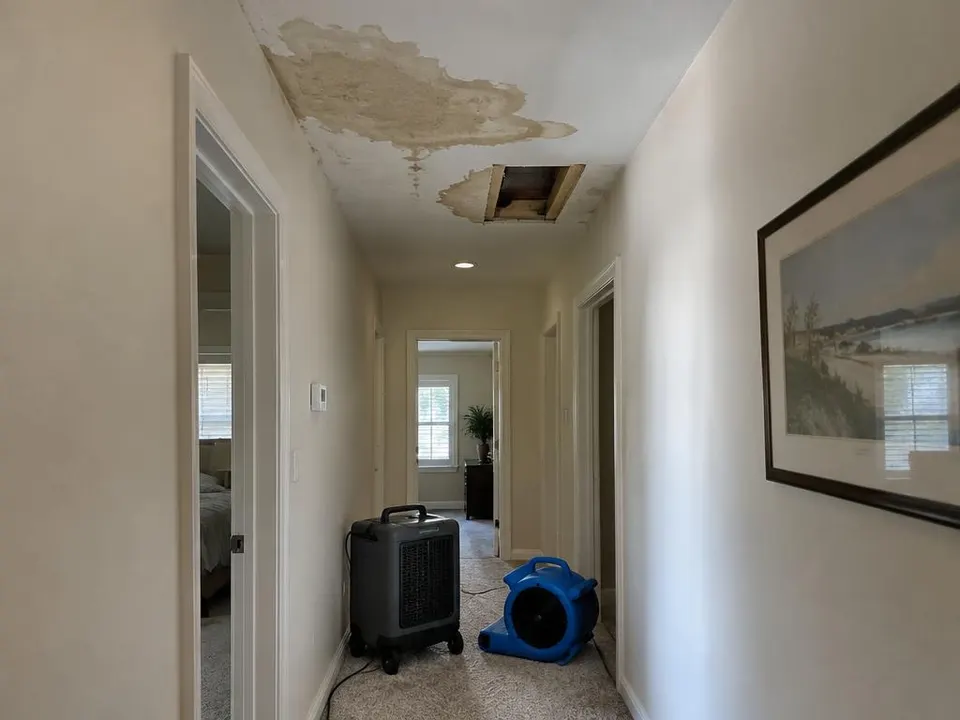
Which facts should be distinguished before a claim discussion?
State when the condition was noticed, what was observed and what a qualified assessor has established. California's insurance department describes sudden accidental damage as typically covered and flood/seepage among typical exclusions, then tells readers to examine their own policy wording. Do not label an uncertain event to fit a desired outcome.
What can be gathered without entering the loss?
Read the policy number and insurer contact from a safe room. Note the timeline; ask the insurer what supporting material it wants and whether it can be supplied without hazardous entry. No part of this guide asks for photos taken in a damaged room.
Stay away from the affected area, do not touch electrical switches, outlets or appliances near water, and call a professional. If anyone is in danger, leave the area and call 911.
Who decides about the bid and payment?
An independent provider states its assessed work and price. The insurer makes a claim-specific decision under the actual contract. Use the estimate-reading guide to ask which tasks are included; it cannot commit an insurer to pay.
Calls go to voicemail, not a live provider. Messages are recorded and transcribed after the greeting. You can email us instead.
Free for homeowners. We may be paid for qualifying referral calls.
Sources
- California Department of Insurance, Residential Insurance Guide (accessed October 11, 2026).
- U.S. EPA, Flood Cleanup to Protect Indoor Air and Your Health (accessed October 11, 2026).
- California Contractors State License Board, Check a License (accessed October 11, 2026).